 Reading Time: 8 mins #
 This post may contain affiliate links.
Money isn’t just a medium of exchange—it’s a mirror—it reflects our values, fears, aspirations, and perhaps most critically— our temperaments. In romantic, familial, or professional relationships, how individuals approach money can be either a unifying force or a silent wedge. Disagreements over finances are consistently cited as a leading cause of conflict. Yet, few of us have ever been taught how to harmonize financial decision-making with someone who sees the world differently.
Understanding financial temperaments—your intrinsic emotional and behavioral patterns related to money—is key to reducing tension—and strengthening the foundation of your relationship.
“Challenges are what make life interesting. Overcoming them is what makes life meaningful.” – Joshua Marine.
The Role of Financial Temperaments in Partnerships
Your financial temperament influences everything from spending and saving to how you react to financial stress. Just as love languages shape how we give and receive affection, financial temperaments shape how we make and interpret financial decisions. In relationships, understanding your tempera
The Four Core Financial Styles
Identifying your financial temperament is a powerful self-awareness tool.
Most people fall into one or more of the following categories:
- The Saver: Disciplined and future-focused, savers thrive on structure, budgets, and conservative investments—they often experience anxiety around debt or financial uncertainty.
- The Spender: Driven by present enjoyment and emotional gratification, spenders may prioritize lifestyle and experiences—they can be generous and spontaneous but may overlook long-term planning.
- The Investor: Focused on long-term gains, investors are comfortable with risk and seek opportunities for their money to grow—their optimism and strategy can be a strength but may intimidate more risk-averse partners.
- The Avoider: Often overwhelmed or disinterested in financial matters, avoiders might defer decision-making or procrastinate managing money—their approach can create tension, especially when paired with a more engaged partner.
Understanding these types can demystify behavior and serve as a foundation for constructive financial conversations.
Bridging the Gap: How to Align Financial Goals Amidst Differences
1. Begin with Transparent Communication
Open communication is non-negotiable. Couples and business partners must regularly discuss money matters in a structured, non-judgmental environment. This isn’t just about budgeting—it’s about values. What does financial security mean to each of you? What role does money play in your ideal life?
Use this opportunity to uncover underlying beliefs that may drive your partner’s behavior. For example, a spender might fear missing out on life experiences, while a saver might be reacting to childhood scarcity.
2. Create a Joint Financial Vision
Craft a shared vision that includes short-term desires and long-term financial goals. Even if your temperaments differ, you can usually find overlap. You may want to travel more, while the other prioritizes building a retirement portfolio. With clarity and compromise, both goals can coexist.
Establish a financial plan that addresses the following:
- Emergency savings
- Debt repayment
- Retirement contributions
- Investment strategies
- Discretionary spending
Apps like YNAB (You Need A Budget) or Mint can help map out a plan and monitor progress—shared visibility eliminates ambiguity and encourages accountability.
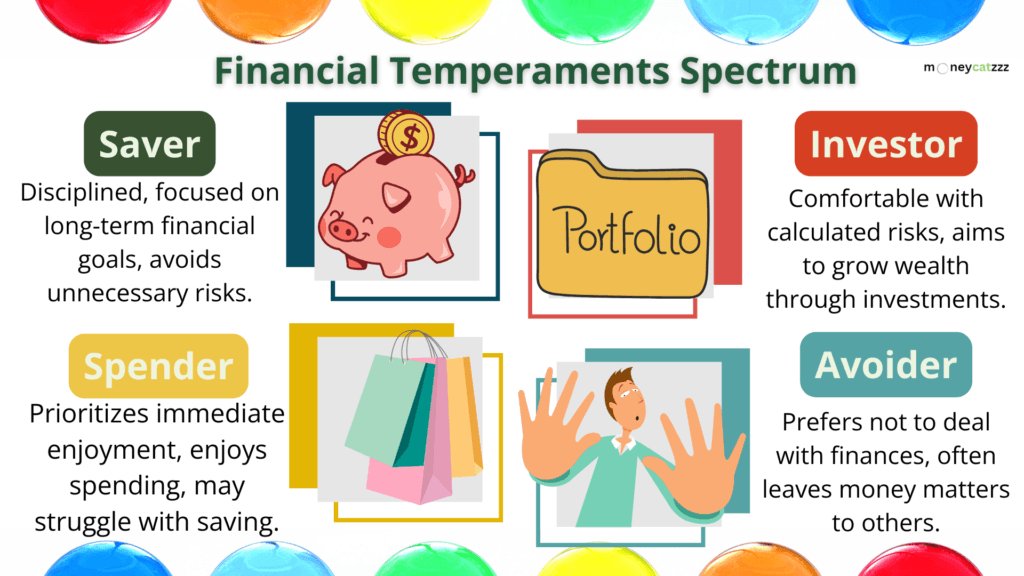
[“Financial Temperaments Spectrum” – Image by moneycatzzz.com]
3. Compromise is Your Secret Weapon
Financial harmony doesn’t require identical views—just mutual respect. For example, a saver can agree to allocate a monthly “fun fund” to honor the spender’s spontaneity while the spender commits to contributing to a joint savings goal.
Mutual concessions don’t dilute your individuality—they affirm your commitment to the relationship. Prioritize flexibility over rigidity.
4. Use Tools That Support Both Styles
Technology offers a suite of tools that can mediate financial differences:
- GoodBudget for envelope-style planning
- Qapital or Digit for automated savings
- Zeta for couples to manage joint and separate accounts
By incorporating these tools—you eliminate the need for constant negotiation and allow each partner to contribute in a comfortable and empowering way.
Navigating Financial Conflict in Relationships
Even with the best intentions, financial disagreements are bound to surface. Here’s how to manage them constructively:
1. De-escalate with Empathy
Listen first. Defensiveness only deepens the divide—instead of accusing, ask clarifying questions:
- “Can you help me understand why this purchase felt important to you?”
- “What were you feeling when we discussed the budget changes?”
These questions invite empathy and uncover the emotional drivers behind financial behavior.
2. Consult Financial or Relationship Experts
Sometimes, an outside perspective is the most valuable. A financial advisor can help craft a balanced strategy, while a therapist or coach can address deeper relational patterns. Seeking professional guidance doesn’t mean failure—it means prioritizing growth.
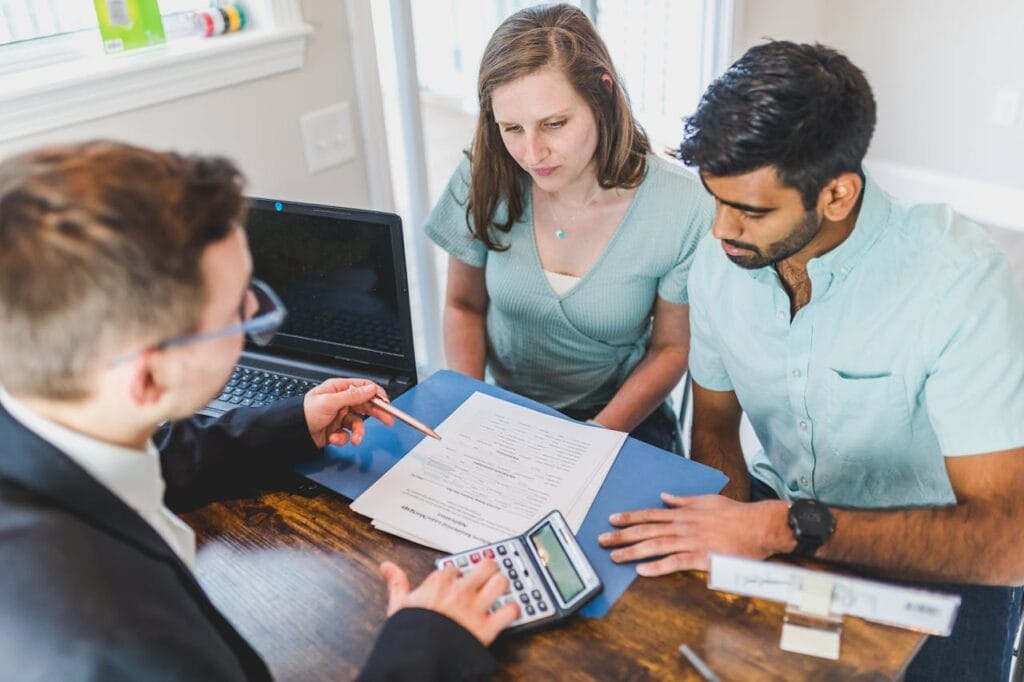
[“Bridging Financial Differences in Relationships” – Photo by RDNE Stock project]
Strengthening Bonds Through Financial Cooperation
While financial disagreements can lead to conflict, they also present an opportunity to deepen trust and connection—couples who confront their differences and work toward shared goals often emerge stronger and more resilient.
Consider:
- Setting quarterly “money dates“ to check in on goals
- Celebrating financial milestones, like paying off a credit card or hitting a savings target
- Reframing challenges as opportunities to collaborate
When financial temperaments are acknowledged and respected—your relationship becomes more than functional—it becomes transformational.
Final Thoughts: Turn Financial Differences Into Relationship Strengths
Uniformity isn’t at the heart of every thriving relationship—it’s mutual respect and the ability to turn differences into assets. When it comes to money, expecting your partner, colleague, or family member to mirror your financial temperament is not only unrealistic—it’s limiting. True success lies in building a system that honors contrast while striving for shared progress.
Think of financial temperaments not as opposing forces but as complementary tools. The spender adds spontaneity and joy, reminding the team or couple to live in the now. The saver brings discipline and foresight, anchoring long-term goals. The investor injects ambition and vision, pushing for growth. The avoider, often overlooked, brings a quiet kind of wisdom—the humility to trust others and the honesty to admit discomfort.
The real power in any relationship—personal or professional—isn’t found in agreeing on every decision but in the shared commitment to navigate differences with empathy, strategy, and curiosity.
Because at the end of the day, it’s not about being the same—it’s about being in sync.
When partners align in numbers and understanding, they avoid financial conflict and build resilient, purpose-driven lives together. And that’s the ultimate wealth.
Disclosure: This post may contain affiliate links. We only recommend products we believe in, and We may receive a commission at no cost to you! Thank you for your support!
Acknowledgment: Cover Photo by Ron Lach
Disclaimer: The information is provided for general information only – moneycatzzz.com makes no representations or warranties in relation to the information, including but not limited to any representation or warranty as to the fitness for any particular purpose of the information to the fullest extent permitted by law. While every effort has been made to ensure that the information provided in this article is accurate, reliable, and complete as of the time of writing, the information provided in this article should not be relied upon to make any financial, investment, real estate or legal decisions. Additionally, the information should not substitute advice from a trained professional who can take into account your personal facts and circumstances, and we accept no liability if you use the information to form decisions.