 Reading Time: 8 mins #
 This post may contain affiliate links.
The Gen Z Financial Revolution: A Paradigm Shift in Global Finance
The Gen Z financial revolution isn’t just a trend—it’s a fundamental reimagining of money, banking, and investing. As digital natives, Gen Z is driving an unprecedented shift toward mobile-first finance, cryptocurrency, decentralized finance (DeFi), and values-based investing. But with these changes come critical challenges: regulatory uncertainty, potential job displacement in traditional banking, and the pressing need for greater financial literacy.
“The future is already here – it’s just not evenly distributed.” – William Gibson.
Mobile Banking & Cashless Payments: The New Standard
Gen Z’s preference for mobile banking is more than convenience—a cultural shift. Digital banks like Chime, Revolut, and Cash App provide frictionless transactions, AI-powered financial management, and even early access to wages. According to The Future of Money, mobile banking is eroding the need for traditional bank branches, forcing financial institutions to rethink their entire business model.
🔹 Impact on Traditional Finance: Brick-and-mortar banks are downsizing while fintech startups thrive. Customer service roles may be replaced by AI-driven chatbots, and traditional banking jobs, like tellers and loan officers, could see steep declines.
🔹 Counterpoint: Over-reliance on digital finance raises cybersecurity concerns. Cyberattacks and fraud risks must be addressed through stronger consumer protections and financial literacy efforts.
Fintech & AI: Algorithmic Finance Takes Over
AI-powered financial assistants like Cleo and Plum help Gen Z automate savings, track spending, and invest effortlessly. The Barefoot Investor emphasizes financial discipline, but in an era of automation, Gen Z trusts AI to handle much of their decision-making.
🔹 Impact on Traditional Finance: AI-driven credit analysis and investment advisory services could replace human financial advisors and analysts.
🔹 Counterpoint: Algorithmic bias in AI-powered finance could exclude underserved communities, reinforcing systemic inequalities.
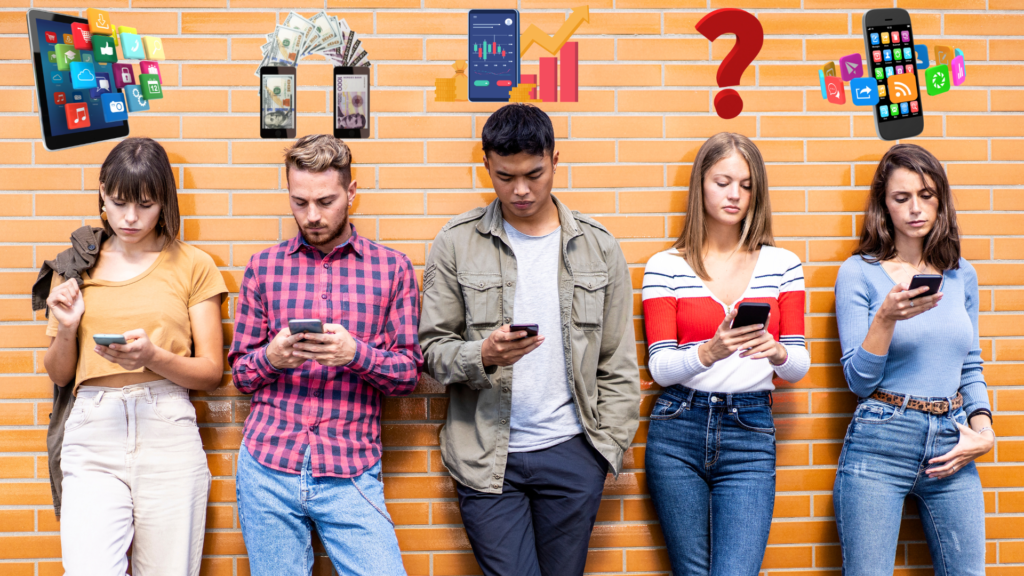
[“Gen Z financial revolution and Finance? ” – moneycatzzz.com with Canva]
The Crypto & DeFi Frontier: Decentralization vs. Systemic Risk
Gen Z’s fascination with cryptocurrency is fueled by its potential to provide financial autonomy and disrupt traditional banking systems. Books like Digital Gold explore Bitcoin’s evolution into a decentralized alternative to conventional banking, while The Age of Cryptocurrency examines how blockchain technology could fundamentally reshape global economies. However, this financial revolution comes with significant challenges, particularly regarding regulation and market stability.
Governments worldwide continue to grapple with how to regulate cryptocurrencies without stifling innovation. The lack of clear policies leaves investors vulnerable to scams, extreme volatility, and market manipulation. Some countries, like Singapore and Switzerland, have begun experimenting with balanced regulatory frameworks to protect consumers while fostering financial innovation. Still, concerns persist. Critics argue that Bitcoin’s high energy consumption and price fluctuations make it an unreliable store of value compared to traditional assets, raising doubts about its long-term viability in mainstream finance.
DeFi’s Rise: A New Financial Order?
Decentralized finance (DeFi) platforms like Aave and Uniswap allow lending, borrowing, and trading without banks. However, The Age of Cryptocurrency warns that DeFi’s lack of oversight makes it susceptible to fraud, “rug pulls,” and market instability.
🔹 Impact on Traditional Finance: Traditional lenders could see reduced relevance as DeFi enables peer-to-peer lending without intermediaries.
🔹 Counterpoint: The complexity of DeFi excludes less tech-savvy users, creating financial barriers rather than eliminating them.
Ethical Investing & Financial Literacy: Aligning Values with Money
Socially Responsible Investing (SRI): A Generation That Invests with Purpose
Gen Z prioritizes ESG (Environmental, Social, Governance) investments. The Future of Money highlights how ethical investing reshapes capital markets, as companies with strong sustainability records outperform those without.
🔹 Challenges: “Greenwashing” remains a problem—companies exaggerate their sustainability efforts to attract investors.
🔹 Potential Solutions: Verified third-party ESG ratings, like those from MSCI or Sustainalytics, can help investors make informed choices.
🔹 Counterpoint: The lack of standardized ESG metrics makes comparing companies’ ethical performance difficult.
Financial Literacy: Bridging the Knowledge Gap
Despite being digital natives, many Gen Z individuals struggle with fundamental financial literacy. While books like The Barefoot Investor advocate for practical money management strategies, the education system often fails to equip young people with essential financial skills. As a result, many enter adulthood without a strong understanding of budgeting, investing, or debt management.
Traditionally, banks played a role in financial education. Still, with Gen Z increasingly bypassing traditional financial institutions in favor of fintech solutions, the responsibility now falls on digital platforms, educational initiatives, and financial influencers. While these resources help bridge the knowledge gap, some argue that financial literacy alone is insufficient. Systemic economic reforms are necessary to address deeper issues of wealth inequality, ensuring that financial knowledge translates into tangible opportunities for all.
[“Gen Z and the Future of Finance” – moneycatzzz.com on Canva]
Emerging Trends: Universal Basic Income (UBI) & Alternative Currencies
As automation reshapes the workforce, discussions around Universal Basic Income (UBI) and digital currencies are becoming more urgent. The Future of Money explores how central bank digital currencies (CBDCs) could work alongside or challenge private cryptocurrencies, offering a new way to distribute wealth in a rapidly changing economy.
UBI could provide financial stability in a world where traditional jobs are disappearing, ensuring a safety net for those displaced by technology. However, skeptics question its long-term sustainability, pointing to the immense costs and potential inflationary pressures. Additionally, while digital currencies promise efficiency and accessibility, they raise concerns about government surveillance and loss of financial privacy.
The Road Ahead
The Gen Z financial revolution is not just about convenience—it’s about redefining finance to be more transparent, decentralized, and aligned with ethical values. However, challenges remain. Regulatory clarity, financial education, and technological adaptation are critical to ensuring this revolution benefits everyone, not just the digitally savvy.
The path forward for traditional banks, fintech firms, and policymakers requires collaboration. The future of money is being rewritten, and Gen Z is holding the pen.
Disclosure: This post may contain affiliate links. We only recommend products we believe in, and We may receive a commission at no cost to you! Thank you for your support!
Acknowledgement: Cover Image by Unsplash.com
Disclaimer: The information is provided for general information only – moneycatzzz.com makes no representations or warranties in relation to the information, including but not limited to any representation or warranty as to the fitness for any particular purpose of the information to the fullest extent permitted by law. While every effort has been made to ensure that the information provided in this article is accurate, reliable, and complete as of the time of writing, the information provided in this article should not be relied upon to make any financial, investment, real estate or legal decisions. Additionally, the information should not substitute advice from a trained professional who can take into account your personal facts and circumstances, and we accept no liability if you use the information to form decisions.