 Reading Time: 8 mins #
 This post may contain affiliate links.
Budgeting for Financial Freedom: Your Roadmap to Financial Independence
Achieving financial freedom isn’t something that happens overnight. It’s a journey that requires planning, discipline, and a commitment to smart money management. Budgeting for financial freedom is essential to ensure that your spending aligns with your goals, enabling you to build wealth, reduce debt, and ultimately gain the freedom to live on your terms.
In this comprehensive guide, we’ll explore essential budgeting strategies, practical tips, and how to navigate emotional and psychological barriers that can hinder your success. Whether new to budgeting or looking to refine your approach, this article will help you build a sustainable financial plan and achieve long-term independence.
Financial freedom is available to those who learn about it and work for it.” — Robert Kiyosaki.
Why Budgeting is Key to Financial Freedom
Many people associate budgeting with restrictive spending, but in reality, it’s about taking Control of your money so that you can make empowered choices. Budgeting helps you prioritize what matters most, whether saving for retirement, paying off debt, or investing in assets that provide financial security.
The key to financial freedom is not just about how much you earn but how much you keep and how effectively you manage it. In You Need a Budget: The Budgeting System That Will Transform Your Life, Jesse Mecham emphasizes that “every dollar has a job.“ This simple principle encourages you to direct your money toward your most important goals rather than letting it slip away through careless spending.
Step-by-Step Approach to Budgeting for Financial Freedom
1. Track Your Spending: Know Where Your Money Goes
Understanding where your money is going is the first step in taking Control of your financial future. Tracking every expense can identify areas where you can reduce spending and reallocate funds to your financial goals. Tracking also highlights unnecessary costs, which are crucial to eliminating if you’re looking to increase savings.
Tools like Mint, YNAB (You Need a Budget), and PocketGuard are excellent for categorizing your spending and setting limits. By gaining visibility into your spending habits, you can take a more proactive approach to your financial goals.
2. Create a Budget That Supports Your Financial Goals
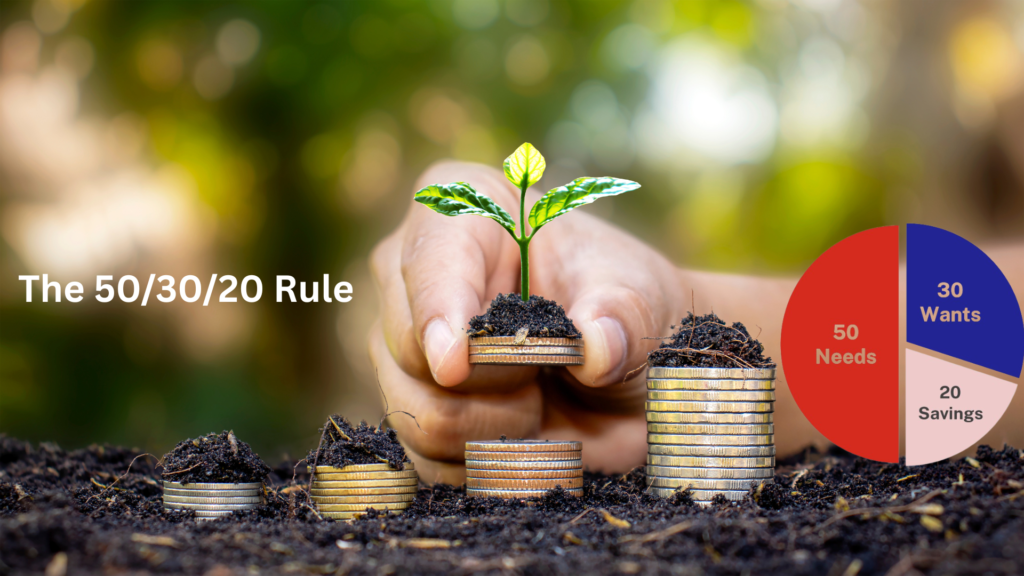
Once you’ve tracked your spending, the next step is to create a budget that works for your financial goals. One of the most widely recommended approaches is the 50/30/20 rule, which helps you allocate your income in a balanced way:
- 50% for needs: Housing, utilities, groceries, insurance, and transportation
- 30% for wants: Entertainment, dining out, vacations, and non-essential spending
- 20% for savings and debt repayment: Building your emergency fund, paying off debt, and saving for future goals
This simple breakdown can help you stay on track and avoid overspending in any category. However, the 50/30/20 rule is just a guideline. It’s important to customize your budget based on your situation.
Tailoring Your Budget to Different Income Levels
- For Low-Income Earners: If you’re living paycheck to paycheck, your needs may take up a larger portion of your budget. In this case, the 50/30/20 rule might need to be adjusted, allocating more to your needs and less to savings or discretionary spending. For instance, you might allocate 70% to needs, 20% to savings, and 10% to wants. The key is to focus on saving something rather than nothing.
- For High-Income Earners: You have more flexibility if you earn a higher income. This allows you to allocate more of your income toward savings, investments, and debt repayment, accelerating your journey to financial freedom. Consider adjusting your budget to allocate 40% to needs, 20% to wants, and 40% to savings and investments.
[“Budgeting for Financial Freedom – The 50/30/20 Rule” Image by moneycatzzz.com]
3. Address the Emotional Aspects of Budgeting
For many, budgeting isn’t just about numbers—it’s also about emotions. Feelings of guilt, frustration, or even fear of financial insecurity can make budgeting seem impossible. However, emotional barriers can be overcome with the right mindset.
In I Will Teach You to Be Rich, Ramit Sethi offers practical strategies for overcoming the emotional hurdles of budgeting. He encourages you to focus on what makes you feel secure while spending consciously. It’s important to remind yourself that budgeting isn’t about deprivation but about achieving financial freedom and aligning your spending with your future goals.
Another critical piece of this emotional journey is learning how to manage stress related to finances. When you feel overwhelmed, remember that small, consistent changes are key to long-term success
4. Automate Your Finances
One of the best ways to stick to your budget is to automate your finances. Automation ensures that your bills, savings, and investments are handled without extra effort. Automation removes the temptation to spend money on things that aren’t essential.
You can set up automatic transfers for recurring expenses, savings goals, or even retirement contributions. This strategy ensures that you’re consistently contributing to your financial goals without thinking about it. Apps like Mint and YNAB offer automated budgeting and savings tools to make this process easier.
5. Celebrate Your Wins and Stay Motivated
Getting discouraged is easy when you’re on a long financial journey. That’s why it’s important to celebrate the small victories along the way. Whether you’ve paid off a credit card, saved $1,000 for an emergency fund, or hit a significant milestone in your savings, take the time to acknowledge your progress.
Celebrating these wins helps keep you motivated and reinforces your developing positive habits. Over time, as your financial freedom becomes a reality, the rewards of your hard work will become more evident.
From Debt to Abundance: How One Woman Transformed Her Finances in Nine Months”
A woman shared her journey on The Sun, explaining how she followed Dave Ramsey’s 7 Baby Steps—cutting up her credit cards, strictly budgeting, and using the debt snowball method—to eliminate all her consumer debt in nine months. Now, she reports saving 17 times more than before, proving that financial freedom is within reach with discipline and the right strategy.
[“Budgeting for Financial Freedom – The Path” – Picture on Canva]
Ramsey’s 7 Baby Steps: A Quick Overview
Inspired by success stories like the above, it’s helpful to understand the foundational plan many use to achieve financial freedom—Dave Ramsey’s 7 Baby Steps. These steps provide a clear, behavioral roadmap to escaping debt and building wealth:
- Save a $1,000 Starter Emergency Fund: Quickly accumulate a small safety net to cover unexpected expenses.
- Debt Snowball: Pay off all non-mortgage debt by targeting the smallest balances first, which builds momentum through quick wins.
- Fully Funded Emergency Fund: Expand your savings to cover three to six months of living expenses, ensuring financial stability in tough times.
- Retirement Investment: Invest 15% of your household income into retirement accounts to secure your future.
- College Savings: Begin setting aside funds for your children’s education.
- Pay Off Your Home Early: Accelerate your mortgage payments to eliminate your biggest debt.
- Build Wealth and Give: Focus on wealth accumulation and give back, cementing your legacy of financial security.
Incorporating these steps into your financial plan creates a structured approach that prioritizes debt repayment and fosters long-term wealth-building habits. The quick wins you experience along the way—much like Sarah’s progress—reinforce your commitment and make the journey toward financial freedom more attainable.
Common Pitfalls to Avoid on Your Path to Financial Freedom
- Ignoring Your Budget: It’s easy to become complacent once you’ve created a budget, but sticking to it is as important as the planning stage. Make sure you review your budget regularly to ensure that it still aligns with your financial goals.
- Underestimating the Importance of Emergency Savings: Life is unpredictable. Make sure to prioritize building an emergency fund. Unexpected expenses can derail your progress toward financial freedom without this safety net.
- Living Beyond Your Means: Achieving financial freedom is difficult if you continually overspend. Stay mindful of your spending and make conscious choices about what’s necessary.
Your Path to Financial Freedom
Budgeting for financial freedom is a journey that requires both discipline and flexibility. The key is creating a budget that works for your income, goals, and lifestyle while tracking your progress. Financial freedom doesn’t happen overnight, but with the right strategies, you’ll be on the path to achieving it.
Start by adopting the 50/30/20 rule, tailoring it to your situation, and staying emotionally connected to your goals. By automating your finances, eliminating unnecessary spending, and celebrating milestones, you’ll create a solid foundation for lasting financial independence.
Remember, budgeting is not just about restricting yourself—it’s about making conscious choices that enable you to achieve financial freedom. Over time, you’ll build wealth, reduce debt, and enjoy peace of mind with financial security.
Disclosure: This post may contain affiliate links. We only recommend products we believe in, and We may receive a commission at no cost to you! Thank you for your support!
Acknowledgement: Cover Image by Unsplash.com
Disclaimer: The information is provided for general information only – moneycatzzz.com makes no representations or warranties in relation to the information, including but not limited to any representation or warranty as to the fitness for any particular purpose of the information to the fullest extent permitted by law. While every effort has been made to ensure that the information provided in this article is accurate, reliable, and complete as of the time of writing, the information provided in this article should not be relied upon to make any financial, investment, real estate or legal decisions. Additionally, the information should not substitute advice from a trained professional who can take into account your personal facts and circumstances, and we accept no liability if you use the information to form decisions.