Financial Literacy 101: A Guide to Essential Financial Products & Services
Financial literacy is the foundation of a secure financial future, yet many find financial jargon confusing. A recent study by The National Endowment for Financial Education found that over 50% of Americans lack basic financial literacy. But understanding financial products & services doesn’t have to be a mystery!
This comprehensive guide empowers you with the knowledge to navigate essential financial products & services, helping you take control of your finances. Whether you’re managing bank accounts, loans, credit cards, or insurance, developing strong financial literacy skills enables you to make informed decisions that shape a stable financial future.
Building Confidence in Financial Management
Financial confidence isn’t something you’re born with—it’s a skill that can be learned and mastered. While it may not feel intuitive initially, consistent effort and the proper knowledge will help you manage your money, optimize financial products & services, and work toward long-term economic stability.
“Financial literacy is the ability to understand and effectively use financial products and services to manage money wisely. It empowers individuals to make informed decisions about saving, investing, borrowing, and protecting their financial well-being.” – Consumer Financial Protection Bureau (CFPB)
Financial Literacy Starts Here: Understanding Bank Accounts
Your bank account is the cornerstone of your finances—think of it as your financial headquarters. It’s where you securely store money, manage daily transactions, and even grow your savings. A solid grasp of financial literacy enables you to make informed choices about different financial products & services, including selecting the right bank account.
Types of Bank Accounts & Their Functions
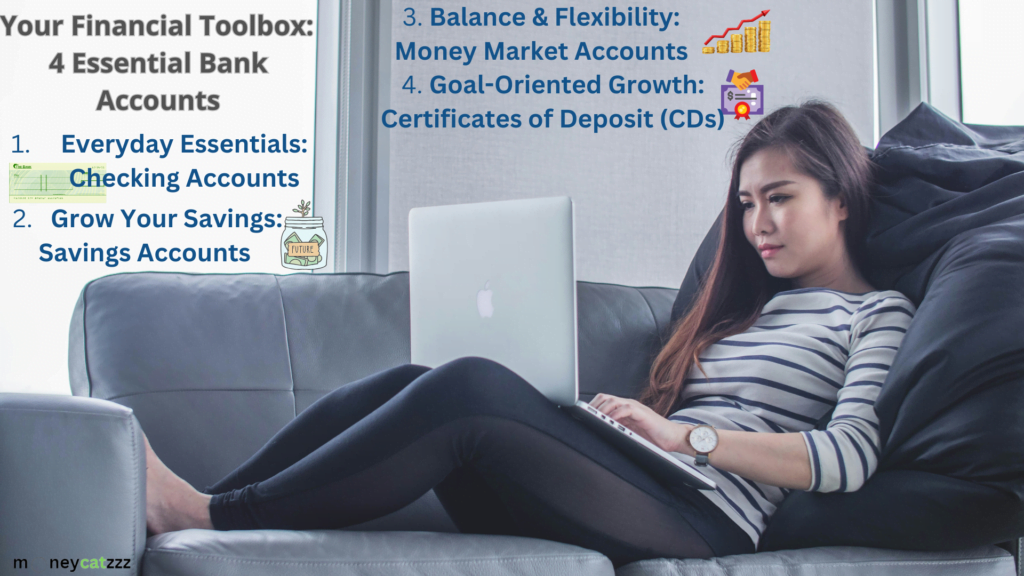
Understanding the various types of bank accounts can help you maximize your financial security and convenience. Here’s a quick breakdown:
- Checking Accounts – Designed for everyday transactions, offering easy access to your money via debit cards, checks, and online banking.
- Savings Accounts – Help you build financial security by earning interest on your deposits while keeping funds accessible.
- Money Market Accounts – A hybrid between checking and savings, providing higher interest rates with limited transactions.
- Certificates of Deposit (CDs) – Lock in funds for a fixed period in exchange for higher interest earnings.
Making Smart Financial Decisions
Strong financial literacy empowers you to make wise banking choices, ensuring your money works for you. When choosing a bank account, consider:
- Monthly Fees & Minimum Balances – Avoid unnecessary costs that eat into your savings.
- Interest Rates & Rewards – Some accounts offer higher yields or cashback incentives.
- Digital & Mobile Banking Features – Essential for convenient money management.
Expanding Your Financial Knowledge: Key Financial Products & Services
Building a strong financial foundation requires more than just understanding bank accounts. To effectively manage your money, you must also master other financial products & services:
Borrowing Wisely: Understanding Loan Options
Loans provide financial support when needed, but responsible borrowing is key. Learn about personal loans, mortgages, auto loans, and student loans, including repayment terms and interest rates.
Navigating Credit: The Power of Credit Cards
Credit cards can be a powerful financial tool if used correctly. Learn how to build credit, avoid high-interest debt, and leverage rewards programs to your advantage.
Protecting What Matters: The Role of Insurance
Insurance safeguards you from unexpected financial risks. Explore different types, such as health, life, auto, and home insurance, to protect yourself and your loved ones.
Your Path to Financial Empowerment
By strengthening your financial literacy and mastering essential financial products & services, you gain the knowledge and confidence to make smart money decisions. The more you understand, the better equipped you are to secure your financial future and easily navigate complex economic systems.
[“The Essential Financial Toolbox” – Photo by Mimi Thian on Unsplash]
Choosing the Right Bank Account
Selecting the right bank account is a critical step in building financial literacy. The right choice ensures your money is managed efficiently and helps you take full advantage of available financial products & services.
Key Factors to Consider
When comparing bank accounts, evaluate:
- Monthly Maintenance Fees – Avoid unnecessary charges that reduce your savings.
- Minimum Balance Requirements – Some accounts waive fees if you maintain a certain balance.
- Interest Rates – Higher interest accounts can help grow your money over time.
- Banking Features – Online banking, mobile deposits, and ATM access enhance convenience.
The Convenience of a Checking Account
A checking account with a debit card simplifies financial transactions. Instead of writing checks or keeping track of due dates manually, you can set up automatic bill payments, ensuring timely payments while avoiding late fees. This is a fundamental financial product that enhances money management.
Borrowing Wisely: Exploring Loan Options
At times, unexpected expenses arise, and financial literacy helps you navigate loan options responsibly. While loans provide essential financial support, borrowing wisely is key to avoiding unnecessary debt.
Common Loan Types & Their Uses
- Personal Loans – A versatile financing option for debt consolidation, home improvements, or major purchases.
- Mortgages – A long-term loan that allows you to purchase a home, making homeownership accessible.
- Auto Loans – Designed to help finance a vehicle, spreading payments over a manageable period.
- Student Loans – Invest in your future by funding education and expanding career opportunities.
The Importance of Responsible Borrowing
Loans can be a powerful financial tool when appropriately managed. To borrow wisely:
- Assess Your Repayment Ability – Borrow only what you can realistically repay.
- Understand Loan Terms – Pay attention to interest rates, repayment periods, and fees.
- Create a Repayment Strategy – Timely payments protect your credit score and financial stability.
By mastering financial literacy and understanding financial products & services, you can make informed decisions that strengthen your financial future. Whether opening a bank account or taking out a loan, strategic choices will help you stay in control of your finances.
Navigating Credit: Credit Cards and Responsible Use
Understanding credit cards is an essential part of financial literacy. They offer convenient access to funds, but responsible management is crucial to avoiding debt and maintaining a healthy credit score.
How Credit Cards Work
A credit card allows you to borrow money up to a set limit, with repayment expected by the due date. Timely payments:
- Build a strong credit score, making qualifying for loans, financial products & services easier.
- Help secure better interest rates on mortgages, auto, and personal loans.
- Prevent late fees and penalties, which can quickly add up.
For a deeper understanding of credit, visit the Consumer Financial Protection Bureau (CFPB).
Responsible Credit Card Use
Using a credit card wisely can enhance your financial health. Follow these best practices:
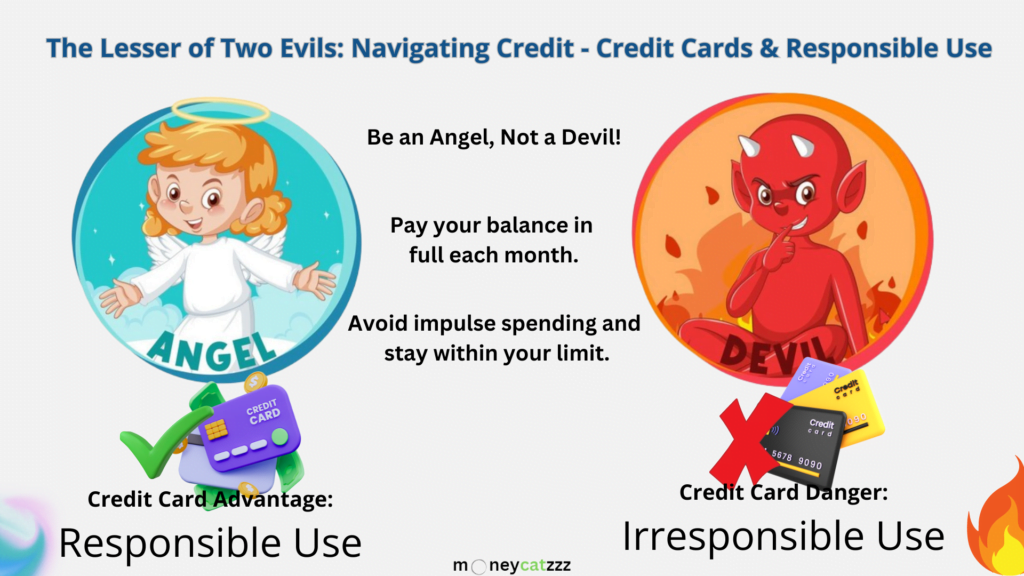
- Pay your balance in full each month – This avoids accumulating interest charges and controls your debt.
- Use credit strategically – Limit purchases to essentials and avoid impulse spending.
- Stay within your credit limit – Exceeding your limit can result in penalties and lower your credit score.
For more details on responsible credit usage, check out MyMoney.gov, a trusted government resource for financial education.
The Rewards Advantage
Many credit cards offer rewards programs, providing perks such as:
- Cashback on everyday purchases
- Travel points and airline miles
- Discounts on dining, shopping, and entertainment
While credit card rewards can be beneficial, always prioritize paying off your balance to maximize benefits without falling into debt.
By improving your financial literacy and understanding of financial products & services, you can make informed decisions, use credit wisely, and build a strong economic future.
[“The Lesser of Two Evils” – moneycatzzz.com]
Protecting What Matters: Understanding Insurance Products
Life is unpredictable, and financial literacy includes knowing how to safeguard yourself with the right financial products & services. Insurance provides a crucial safety net, protecting you from unexpected financial hardships.
Health Insurance: Your Shield Against Medical Expenses
Medical emergencies can be costly. Health insurance helps cover hospital bills, doctor visits, and prescriptions, reducing out-of-pocket expenses and ensuring access to quality healthcare.
Life Insurance: Securing Your Loved Ones’ Future
Life insurance is a vital financial product that provides a death benefit to your beneficiaries. It helps your loved ones manage financial responsibilities, such as mortgage payments, education costs, or daily living expenses, in the event of your passing.
Auto Insurance: Financial Protection on the Road
Car accidents can result in significant expenses. Auto insurance covers:
- Vehicle damage repairs
- Medical costs for injuries
- Liability for damages to another person’s property
Choosing the right auto insurance policy ensures financial protection in case of an accident.
Home Insurance: Safeguarding Your Property
Your home is a valuable asset. Home insurance provides coverage for:
- Fire, theft, or natural disasters
- Structural damage
- Personal belongings
This type of financial protection helps you recover from unexpected losses without facing severe financial strain.
The Importance of Insurance
Imagine facing a sudden medical emergency. Without health insurance, you could be left with overwhelming medical bills. However, a comprehensive health insurance policy helps cover the costs, preventing financial hardship and ensuring proper care.
By understanding financial products & services like insurance, you control your financial security, making informed decisions that protect your future.
Taking Control: Building a Strong Financial Foundation
Mastering financial literacy is key to taking control of your money. By understanding financial products & services, you can make confident, informed decisions that set the stage for long-term financial security.
Recap and Action Steps
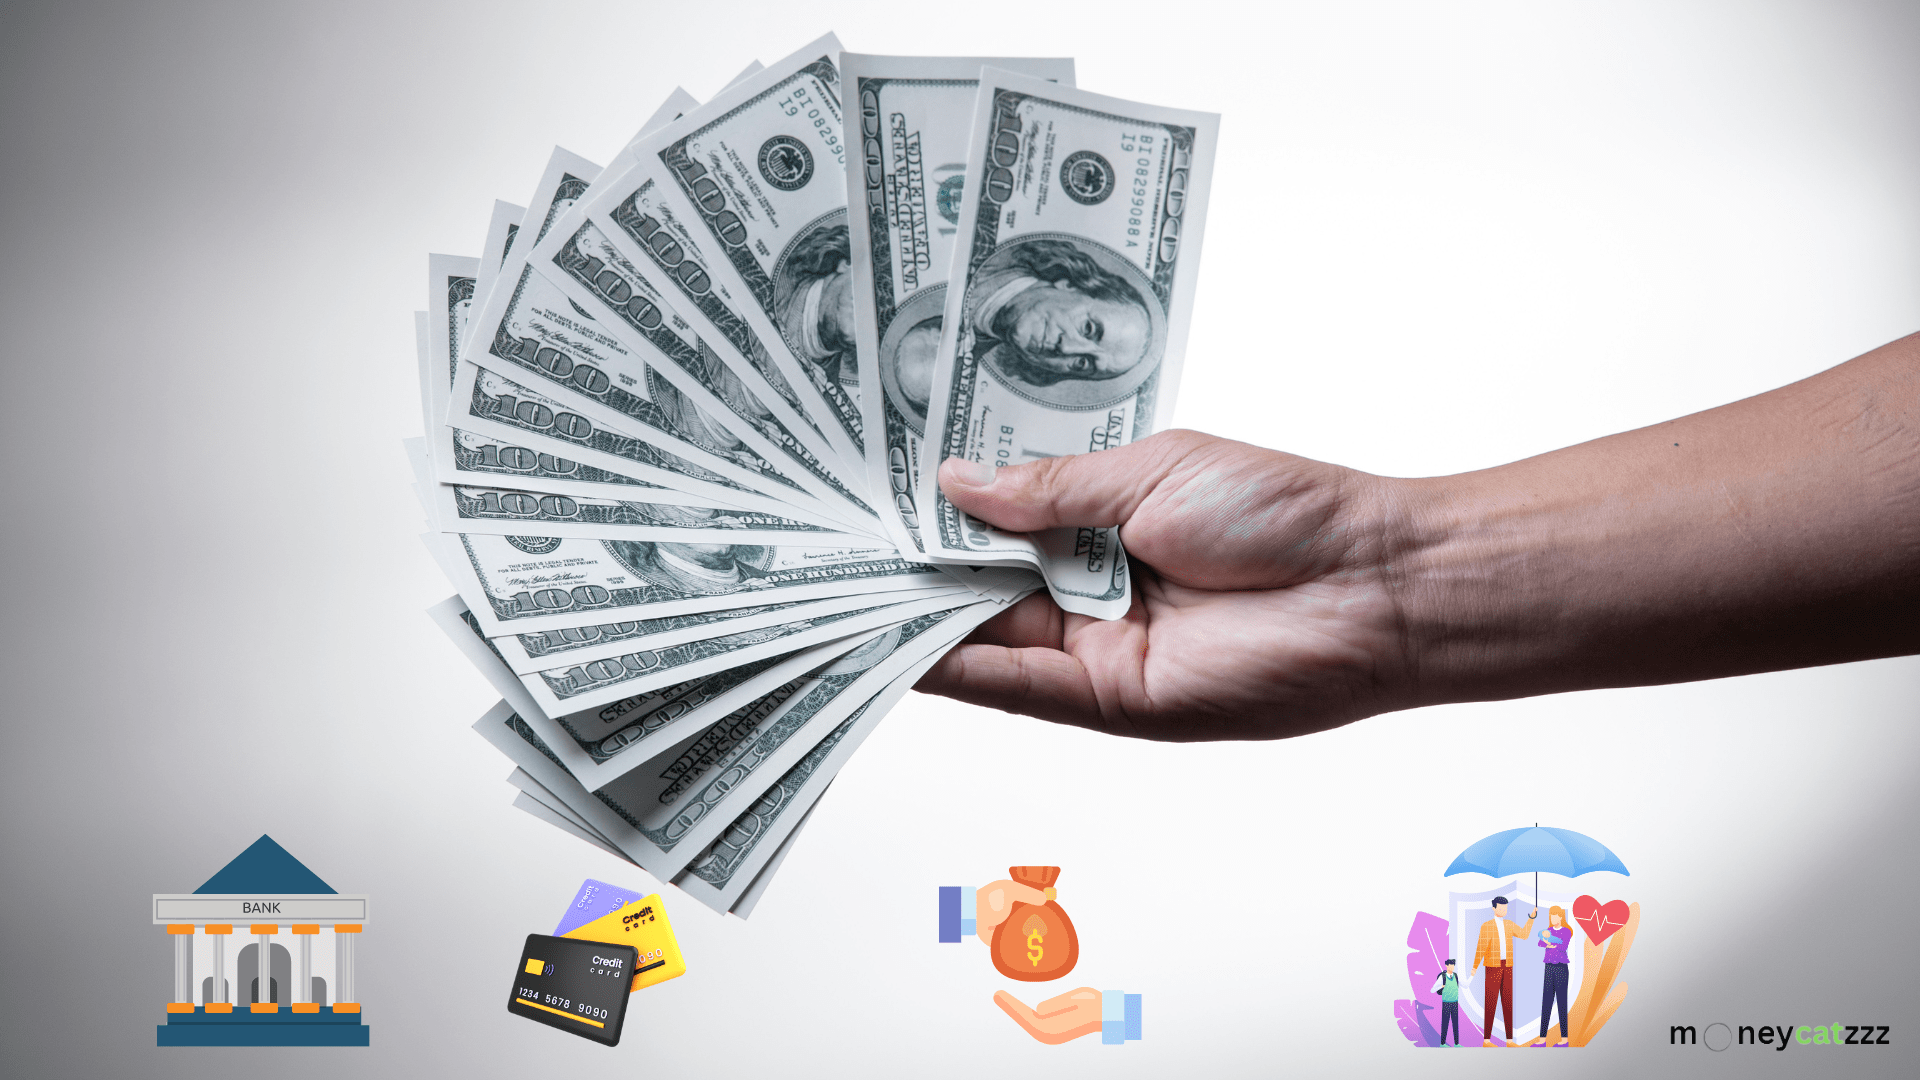
Now that you’ve learned about various financial products & services, it’s time to take action. Review the essential financial tools you’ve encountered, including:
- Bank accounts
- Loans
- Credit cards
- Insurance
By reviewing these products, you can see how they work together to shape a healthy financial future.
Building a Personalized Financial Plan
A solid financial foundation involves setting both short-term and long-term goals. Start by creating a financial plan that aligns with your values and priorities.
Key components of a personalized financial plan include:
- Budgeting your income
- Exploring investment options
- Setting realistic savings goals
Building this plan will help you manage your money effectively, ensuring your financial journey remains on track.
[“Building a Strong Financial Foundation” – Image by freepik]
Debt Management: Taking Control of Your Obligations
Debt can be a valuable financial tool when managed responsibly, but high-interest debt can quickly become overwhelming. Effective debt management helps you take control of your obligations and achieve financial stability.
Prioritize Debt Repayment
A key strategy for managing debt is to focus on paying off high-interest debts first. This could involve methods such as:
- Avalanche method: Targeting debts with the highest interest rates first.
- Snowball method: Pay off smaller debts first to gain momentum and motivation.
These strategies can help you quickly eliminate your debt and save on interest payments.
Develop a Repayment Plan
Create a realistic budget that allocates funds toward debt repayment while covering your essential expenses. The Consumer Financial Protection Bureau offers practical tools and resources to help you build a budget and manage debt effectively.
Explore Debt Consolidation
Debt consolidation can be a powerful option for simplifying your debt repayment process. By consolidating multiple high-interest loans into one loan with a lower interest rate, you reduce the complexity and make it easier to manage payments. Learn more about debt consolidation options and how they could work for you.
Building a Good Credit Score is Key
A good credit score plays a crucial role in managing debt effectively. It reflects your creditworthiness and makes it more likely that you will qualify for loans with lower interest rates, saving you money over time. Maintaining a solid credit score will help you:
- Reduce the cost of borrowing.
- Qualify for favorable financial products.
- Make debt repayment more manageable.
Focus on paying down debt responsibly, avoid taking on additional high-interest loans, and work on improving your credit score.
Savings Strategies: Building Your Financial Future
Saving consistently is one of the most effective ways to build a secure financial future. By implementing the right savings strategies, you can confidently reach your financial goals.
Create an Emergency Fund
An emergency fund is essential for handling unexpected costs, such as medical expenses, car repairs, or job loss. Aim to save at least 3-6 months of living expenses to ensure you have a financial safety net. Learn more about building an emergency fund and its importance for financial well-being.
Retirement Savings: Start Early!
Retirement may seem far off, but the earlier you start saving, the better. There are several options to consider for retirement savings, such as:
- Employer-sponsored plans (like 401(k)s) may include company contributions.
- Individual Retirement Accounts (IRAs), which offer tax advantages.
Starting early gives your money more time to grow, which is essential for a comfortable retirement. Explore retirement savings options to see which is best for you.
Harness the Power of Compound Interest
Compound interest is one of the most powerful tools for building wealth over time. When you save money in an interest-bearing account, your interest begins to earn additional interest. The earlier you start, the more your money can benefit from compound interest and grow exponentially.
Consumer Protection: Be Aware of Hidden Fees
When managing your finances, it’s essential to be aware of hidden fees that may not be immediately obvious. Financial institutions may charge fees that can quickly add up, eroding your hard-earned money. Let’s take a look at some common fees to watch out for.
Bank Accounts: Watch Out for Hidden Fees
While bank accounts are meant to help manage your money, there are often fees associated with them. Some common hidden fees include:
Monthly maintenance fees: Many banks charge a monthly fee for maintaining your account.
ATM withdrawal fees: These fees can apply, especially when withdrawing from out-of-network ATMs.
Minimum balance fees: Falling below a required minimum balance can result in penalties.
Inactivity fees: If your account is unused for a long time, some banks may charge an inactivity fee.
Credit Cards: Hidden Fees Can Add Up
Credit cards offer convenience, but they also come with potential hidden fees. These may include:
Annual fees: Many credit cards charge an annual fee just for owning the card.
Late payment fees: Missing a payment can lead to hefty late fees.
Foreign transaction fees: When using your card internationally, you may incur additional charges.
Cash advance fees: Withdrawing cash from an ATM using your credit card can result in a fee.
Balance transfer fees: If you transfer debt from one card to another, you might face a fee.
Other Financial Products: Watch for Fees
Aside from bank accounts and credit cards, other financial products may have hidden fees. For example:
Early termination fees: These can apply if you cancel services like insurance before the contract ends.
Application fees: Some loans or financial products & services may charge an application fee.
Statement fees: If you prefer paper statements, you may incur a fee—often avoidable by opting for online statements.
Protect Yourself from Fees
Carefully review bank statements and credit card agreements to identify and avoid these fees whenever possible. You can also consider institutions known for lower fees or those offering fee waivers when you meet certain criteria, such as maintaining a minimum balance. Learn more about consumer protections.
Real-Life Success Stories: Applying Financial Literacy to Achieve Financial Goals
Case 1: Balancing Debt & Dreams (Debt Management)
Leigh, a young professional, dreamed of owning a home but was weighed down by debt. After discovering the power of financial literacy, Leigh created a detailed plan to manage her financial products & services effectively. Using budgeting apps like Mint to track her expenses, she prioritized paying off high-interest debt and found ways to save more.
By combining smart debt management and a commitment to financial planning, Leigh achieved her dream of homeownership in just three years. This story highlights how financial literacy can empower individuals to make informed decisions and turn dreams into reality.
Case 2: Teaching Kids About Money (Financial Literacy for Families)
The Miller family wanted to raise financially responsible children. With the guidance of a financial literacy guide, they began to discuss important money concepts with their kids and incorporated age-appropriate activities. They also used budgeting apps designed for kids, like Greenlight, which made learning about money fun and interactive.
The Millers fostered a positive relationship with money in their family by involving their children in discussions about financial products & services and money management from an early age. This approach not only helped their kids develop good habits but also set them up for economic success in the future.
These case studies demonstrate how financial literacy can be applied to improve financial decision-making in real-life scenarios. Whether managing debt or teaching children about money, this knowledge can lead to better financial outcomes.
[“Knowledge is King” – Photo by Gabriella Clare Marino on Unsplash]
Take Control: Mastering Your Financial Future Through Continued Learning
Financial literacy is an ongoing journey that empowers you to build a secure and prosperous future. With the insights shared in this guide, you’ve already made a significant move toward financial independence. The following steps are yours to take.
Your Next Steps for Financial Success
Continue Expanding Your Knowledge
Books to Guide You:
- “I Will Teach You To Be Rich“ by Ramit Sethi: A practical guide to wealth-building strategies, budgeting, and investing.
- “The Psychology of Money“ by Morgan Housel: Understand the psychology behind money and develop healthier financial habits.
- “Broke Millennial“ by Erin Lowry: A targeted resource for young adults navigating debt, building credit, and achieving financial freedom.
Turn Knowledge into Action
Apps to Boost Your Financial Skills:
- Mint: A free app to track spending, set budgets, and manage goals. Mint helps categorize spending and find areas to cut back.
- YNAB (You Need a Budget): A subscription-based app for proactive budgeting, helping you allocate your income to achieve specific goals.
- Digit: Automatically transfers small amounts into savings, making it easy to grow your savings effortlessly.
Remember, financial literacy is a continuous process. Keep refining your financial strategies, learning, and adjusting your plan to stay on track. With consistency and dedication, you’ll be on the path to achieving your financial goals and securing a bright future for yourself and those you care about.
We wish you success on your financial journey!
Financial Literacy Glossary:
- Interest Rate: The cost of borrowing money expressed as a percentage.
- Credit Score: A numerical representation of a borrower’s creditworthiness, impacting loan eligibility and interest rates.
- Annual Percentage Rate (APR): The annual cost of borrowing money, including interest and fees.
Disclaimer:
The information provided in this article is for general educational purposes only and does not constitute financial advice. Please consult a qualified financial advisor for personalized guidance tailored to your financial situation and goals.
Signup to our Newsletter for regular updates:
Disclaimer: The information is provided for general information only – moneycatzzz.com makes no representations or warranties in relation to the information, including but not limited to any representation or warranty as to the fitness for any particular purpose of the information to the fullest extent permitted by law. While every effort has been made to ensure that the information provided in this article is accurate, reliable, and complete as of the time of writing, the information provided in this article should not be relied upon to make any financial, investment, real estate or legal decisions. Additionally, the information should not substitute advice from a trained professional who can take into account your personal facts and circumstances, and we accept no liability if you use the information to form decisions.